
PUGALENTHI
Updated on 30-07-2026
It's important to fully understand the various types of GST Returns in order to comply with the Goods and Services Tax (GST) requirements. This article specifically covers 2 important GST Returns, GSTR-1 and GSTR-3B. It will explain what each of these Returns is intended to accomplish, what information should be included in each Return, how frequently they need to be filed and the differences between them. You should have an overview of GSTR-1 and GSTR-3B and why they should be completed with accuracy.
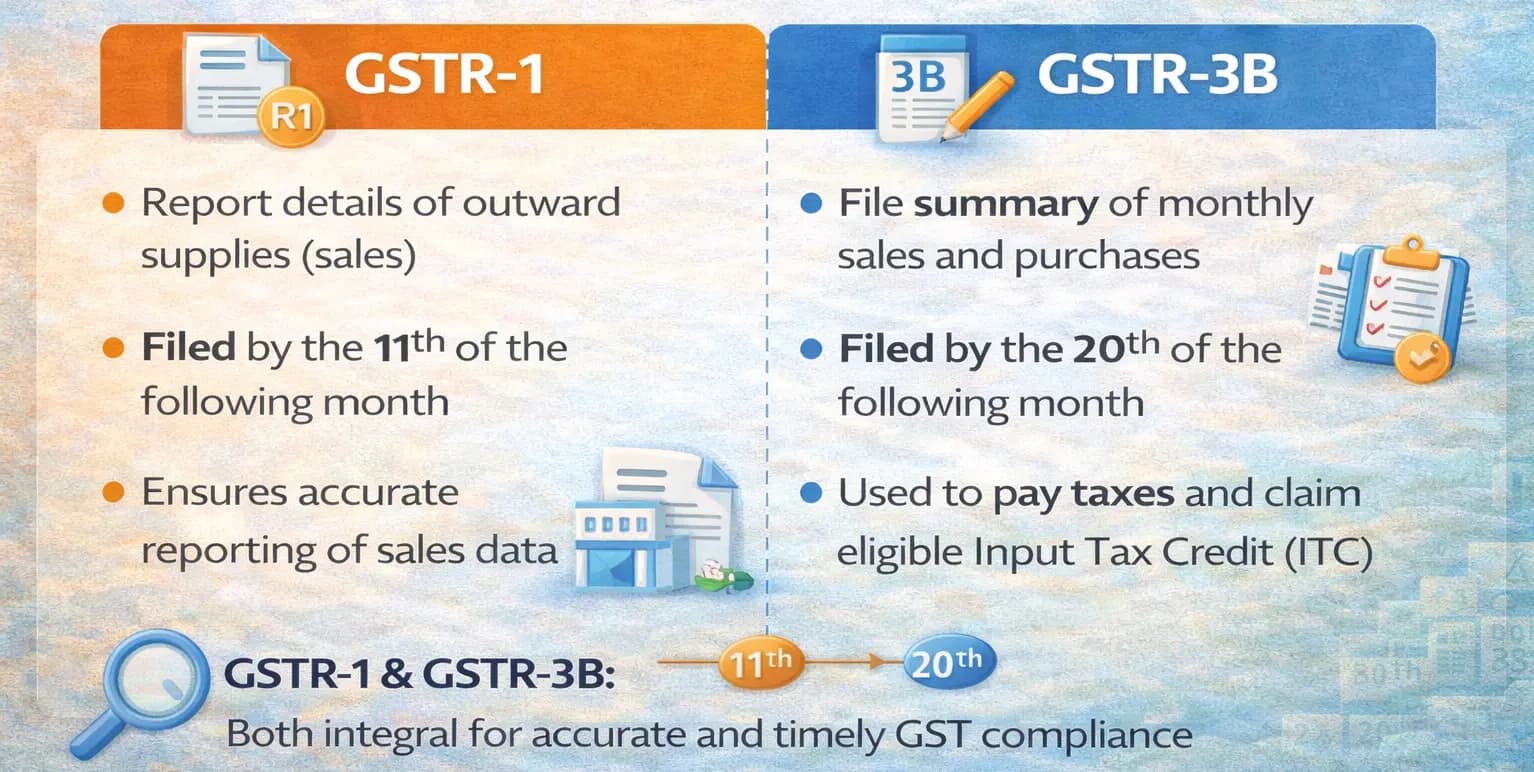
The GSTR-1 return captures the details of the outward supplies of Goods and Services through either a month-to-month or quarterly filing. The GSTR-1 shows the complete picture of the taxable supplies (whether intra-state, zero-rated or deemed export transactions).
You can file GSTR-1 monthly or quarterly, depending on your annual turnover:
GSTR-3B is a monthly self-declaration that summarizes the total values of sales and input tax credit. It's a simpler, provisional return intended to help taxpayers discharge their tax liabilities.
Unlike GSTR-1, GSTR-3B must be filed monthly by all regular taxpayers. The deadline is the 20th of the following month, though this may vary as per notifications issued by the government.
While GSTR-1 offers both monthly and quarterly filing options based on the taxpayer's turnover, GSTR-3B is strictly a monthly obligation for all.
GSTR-1 requires granular details of each transaction, making it a more detailed and comprehensive return. In contrast, GSTR-3B is a summarized return providing a high-level overview of sales and tax liabilities.
Together, GSTR-1 and GSTR-3B ensure comprehensive GST compliance:
Thus, both returns act in tandem to maintain the GST ecosystem, emphasizing the importance of accuracy and timely submission.
Taxpayers need to understand that GSTR-1 and GSTR-3B returns are used in different ways under the GST compliance framework. The GSTR-1 filing provides tax payers with necessary information in order to create their GSTR-3B return. The information in GSTR-1 enables tax payers to reconcile their payments against the details reported in GSTR-1 to ensure that their tax obligations are met. GSTR-1 and GSTR-3B are crucial in the GST system, and completing accurate GSTRs is essential for all tax payers. Taxpayers must be aware of the main function of each type of GSTR and submit GSTR-1 and GSTR-3B together because they are interrelated and thus together complete the GST process.
LEDGERS simplifies GST compliance by embedding reconciliation directly into the accounting workflow, helping businesses identify mismatches early and address them before they lead to interest or penalties. With automated GSTN data synchronization, invoice-level tracking, and system-driven validations, LEDGERS enables seamless, reliable compliance without last-minute corrections or manual follow-ups.
